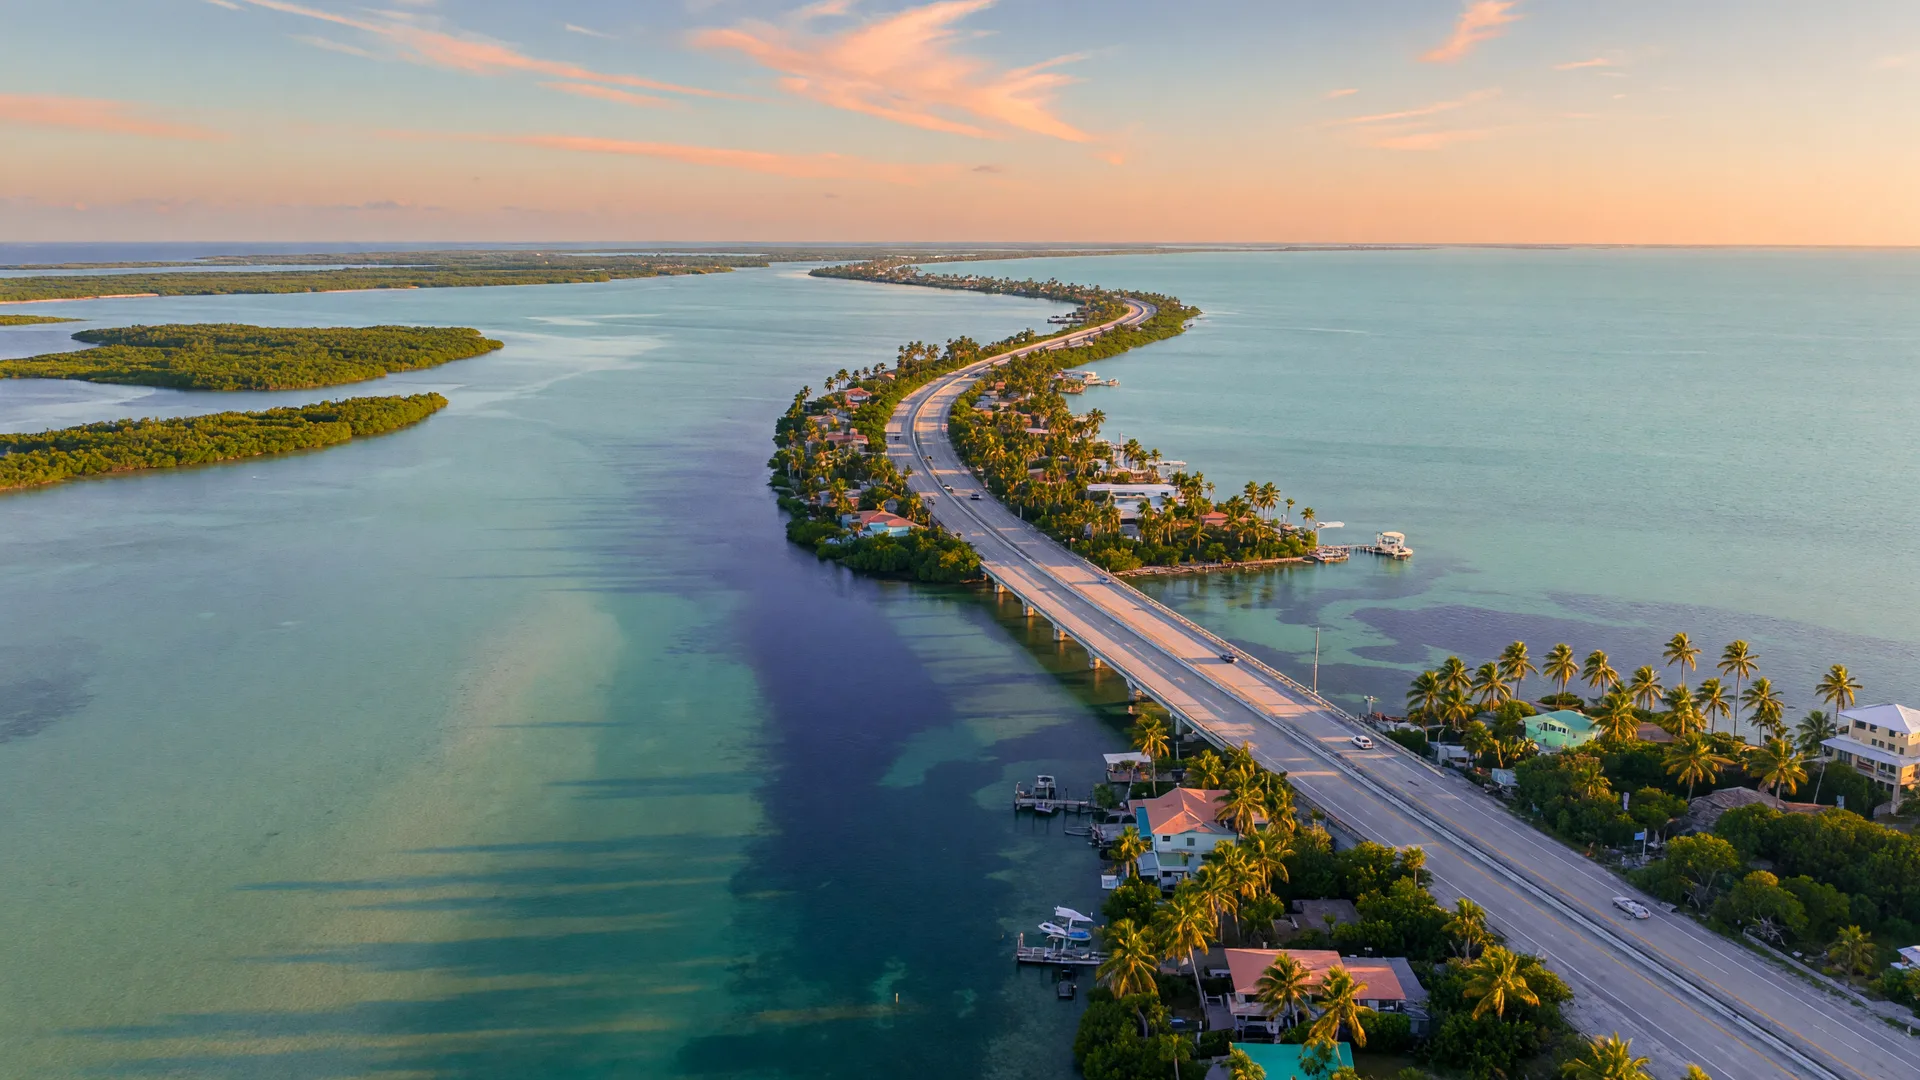
The Florida Keys housing market is one of the tightest in the country in late 2026. Monroe County's median sale price hit $1.1 million in June, up 30% from a year earlier, while 30-year mortgage rates climbed back above 7% in early October. If you are shopping in Key Largo, Islamorada, or Marathon, here is what the numbers actually mean and how to put together a financing plan that works.
This is not a market you can shop casually. Supply is shrinking, demand is strong, and a meaningful share of offers are all cash. That combination makes preparation matter more than almost anywhere else in Florida.
Let's break down the latest data by area, talk about what the October rate move changes, and go through the financing realities that trip up Keys buyers who come in unprepared.
The Keys Market Right Now: Tight Supply, Record Prices
The headline number is the median sale price for residential properties across Monroe County: $1.1 million in June 2026, up 30% year over year. That was the sharpest gain of the year, and it followed a May median of $965,000, up 12%. Prices in the Keys have been climbing, not cooling.
The driver is supply. Active inventory across the Keys fell 9.5% to about 1,418 homes, new listings were down 7%, and pending inventory rose 20%. In the first quarter of 2026, sales of all property types grew 13.6% while the average sale price climbed 13.4% to about $1.22 million. Luxury listings fell roughly 22% year over year in Q1 even as luxury sales rose about 20%, which tells you how much demand is chasing a shrinking pool of high-end homes.
The brief price softness some buyers saw in late 2025 and early 2026 has reversed. Leverage has shifted back to sellers, and waterfront properties in particular are drawing multiple offers.
Key Largo, Islamorada, and Marathon: Three Different Markets
The Keys are often talked about as one market, but the Upper, Middle, and Lower Keys behave differently. Here is what the most recent published data shows for the three areas buyers ask about most.
Key Largo
Key Largo is the most accessible market in the Keys, about an hour from Miami, and it has the deepest inventory. The median sale price is around $980,000, up about 20% year over year, with roughly 390 active listings and homes pending in about 88 days on average. Zillow's typical home value sits near $1.1 million.
For buyers, Key Largo offers the widest range of price points in the Keys, from older canal homes to newer single-family properties. It is also the most practical choice for someone who wants to stay connected to the mainland for work or family.
Islamorada
Islamorada, the sportfishing capital of the world, sits at the higher end of the market. The median sale price is around $1.4 million, up more than 50% year over year, and the typical home value is roughly $1.43 million. Inventory is thin, with median list prices well above $2 million in recent months.
This is a market where the home itself is only part of the story. Deep-water docks, direct ocean access, and the village's reputation drive premiums that do not show up in a simple price-per-square-foot comparison. If Islamorada is your target, expect to compete for the handful of listings that fit your criteria.
Marathon and the Middle Keys
Marathon anchors the Middle Keys, and it has been the fastest-moving part of the chain. The median sale price is around $1 million, up more than 40% year over year over the last three months, with roughly 275 active listings. The Middle Keys led the Keys in sales-volume growth at 23% while active listings dropped 8.5%.
Marathon tends to offer more variety than Islamorada, including canal homes, bayfront properties, and some of the more attainable price points in the Middle Keys. If you want a true Keys lifestyle with more inventory to choose from, this is the area to watch.
The October 2026 Rate Environment: What Changed
Mortgage rates moved up sharply in early October. Freddie Mac's Primary Mortgage Market Survey put the average 30-year fixed rate at 7.28% for the week ending October 1, up from 7.03% the week before and 6.34% a year earlier. Daily surveys from Bankrate and other trackers showed rates around 7.4% to 7.55% in the first days of October.
That is a meaningful jump, and it matters more in the Keys than almost anywhere else because the loan sizes are so large. On a $1 million mortgage, moving from about 6.5% to 7.25% adds roughly $500 a month to your principal and interest payment. Over 30 years, that is more than $180,000 in extra interest.
Forecasts for the rest of 2026 vary. Fannie Mae's latest outlook sees rates averaging around 6.8% for the year, the Mortgage Bankers Association projects about 6.5% for the fourth quarter, and other forecasters expect rates to stay near or above 7% through the fall and winter unless inflation cools enough to change the Federal Reserve's path. The honest answer is that nobody knows, which is why trying to time the market is usually a losing game.
How Financing Works in the Keys
The Keys are a financing market with its own rules. Here is what I tell every buyer who calls me about Key Largo, Islamorada, or Marathon.
Most Keys homes need jumbo financing
The 2026 conforming loan limit is $832,750 in most of Florida, and Monroe County is a high-cost area with limits up to $1,249,125. With median prices around $1 million and up, a large share of Keys purchases fall into jumbo territory. Jumbo loans have their own credit, down payment, and reserve requirements, so it pays to talk through them before you make an offer. I wrote a full guide to jumbo loans in Florida if you want the details.
Insurance is a budget line, not an afterthought
Flood insurance is required for most Keys properties, and windstorm coverage is a major cost on top of standard homeowners insurance. FEMA's Risk Rating 2.0 prices each property individually, so two similar homes can carry very different premiums depending on elevation and flood history. Get real quotes before you fall in love with a house. A home that looks affordable on paper can be out of reach once insurance is in the payment. My flood insurance guide walks through how this works.
You will compete with cash
A large share of Keys offers are all cash, especially at the luxury end. That does not mean financed buyers cannot win, but it means your pre-approval needs to be thorough, your lender needs to be responsive, and your offer should show the seller you can close without drama. A fully documented pre-approval from a lender who knows the Keys goes a long way.
Second-home buyers face different rules
Many Keys buyers are purchasing a second home or vacation property, and those loans come with higher down payment requirements and different occupancy rules than a primary residence. If the property will generate rental income, the financing picture changes again. My guide to second home and investment financing covers the differences.
Condo buyers need a warrantable building
If you are looking at a Keys condo, the building itself has to meet Fannie Mae, Freddie Mac, or FHA requirements, including reserve funding and insurance coverage. Post-Surfside rules have made this stricter, and some buildings simply do not qualify for conventional financing. Check the building's financial health before you make an offer, not after.
I believe an educated buyer makes better financial decisions. My job isn't to sell you a mortgage. It's to help you understand your options, avoid costly mistakes, and choose the financing strategy that truly fits your goals.
Austin Edwards, Mortgage Loan Originator · NMLS #2639747
What This Means for Buyers This Fall
Fall is historically a quieter season in the Keys. The summer crowds thin out, and buyers who are still shopping tend to be serious. With inventory this tight, the seasonality matters less than it does in other Florida markets, but it is still a reasonable time to look.
The practical advice has not changed, but it matters more now. Get pre-approved before you look, budget the full monthly payment including insurance, flood, and taxes, and be ready to move when the right property comes up. In a market where the median home costs seven figures and rates are above 7%, the buyers who win are the ones who did their homework first.
Key Takeaways
- Prices are at record highs. Monroe County's median hit $1.1 million in June 2026, up 30% year over year, driven by shrinking inventory and strong demand.
- Each area is different. Key Largo offers the most inventory around $980,000, Islamorada runs higher near $1.4 million, and Marathon is the fastest-moving market near $1 million.
- Rates jumped in October. The 30-year average hit 7.28% in the first week of October, up from 6.34% a year earlier, adding roughly $500 a month on a $1 million loan.
- Financing is specialized. Most Keys homes need jumbo loans, flood and windstorm insurance are major costs, and cash competition means your pre-approval has to be strong.
- Get pre-approved first. Whether you are buying in Key Largo, Islamorada, or Marathon, a thorough pre-approval makes your offer competitive and tells you exactly where you stand.
Frequently Asked Questions
Is the Florida Keys housing market going to crash?
There is no data pointing to a crash. The Keys are supply-constrained, with inventory down nearly 10% and prices up 30% year over year as of mid-2026. A market with that little inventory does not usually crash; it more often cools slowly if demand fades. That said, affordability at these prices and rates is a real challenge, and buyers should stress-test their budget.
Can I buy a home in the Keys with a conventional loan?
Yes, up to the conforming limit, and Monroe County's high-cost limit is $1,249,125 in 2026. Homes above that need jumbo financing, which has its own requirements for down payment, credit, and reserves. Many Keys purchases fall into jumbo territory, so it is worth reviewing your plan with a lender before you shop.
Do I need flood insurance for a Keys home?
Almost certainly yes. Lenders require flood insurance on properties in FEMA-designated flood zones, which covers most of the Keys, and windstorm coverage is a separate and significant cost. Premiums under Risk Rating 2.0 vary by property, so get real quotes early and build them into your budget.
Is it cheaper to buy in Key Largo or Islamorada?
Key Largo is generally more attainable, with a median sale price around $980,000 and the most inventory in the Keys. Islamorada runs higher, around $1.4 million, with thinner supply and median list prices well above $2 million in recent months. Marathon sits between them and has been the fastest-moving market.
Can I use a VA loan in the Florida Keys?
Yes, VA loans work in the Keys for eligible veterans and active-duty buyers, including zero-down financing. The main considerations are the higher loan amounts, flood and windstorm insurance costs, and making sure the property and any condo building meet VA requirements. A lender who knows VA plus the Keys can walk you through it.
Should I wait for mortgage rates to drop before buying in the Keys?
Rates could ease, but prices in the Keys are climbing while supply shrinks, so waiting has a real cost. If you find a home that fits your budget and your plan, buying when you are ready beats gambling on a rate change that may not come. You can always refinance later if rates improve.
Austin Edwards
Mortgage Loan Originator · NMLS #2639747
Austin helps Florida homebuyers and homeowners understand their options and make confident mortgage decisions. He believes an educated borrower makes better financial choices.
More Resources
For more context on buying in the Keys, check out our guides on jumbo loans for high-value homes, flood insurance in Florida, and second home financing. Or reach out to Austin directly with your specific questions.
Have a question? Ask Austin.
Every buyer's situation is different. If something in this article raised a question about your own plans, Austin would love to hear from you. No commitment, no sales pitch. Just a straight answer.
Ask Austin a QuestionReady to make your move?
Get pre-approved or schedule a free consultation with Austin. He will walk you through your options, explain the numbers, and help you build a plan that fits your goals.